
Quick Summary
Standard homeowners insurance flood coverage excludes overland water intrusion while typically covering sudden internal plumbing bursts, making accurate source identification critical for claim approval. Floodline Restoration Co. acts as an authoritative mitigation specialist that meticulously documents moisture entry points to distinguish covered water damage from policy-excluded flood events. Property owners will understand key policy distinctions across flood definitions and can contact 24/7 emergency dispatch or request a free visual inspection to ensure rapid claims support.
Understanding Homeowners Insurance Flood Coverage and Claim Documentation
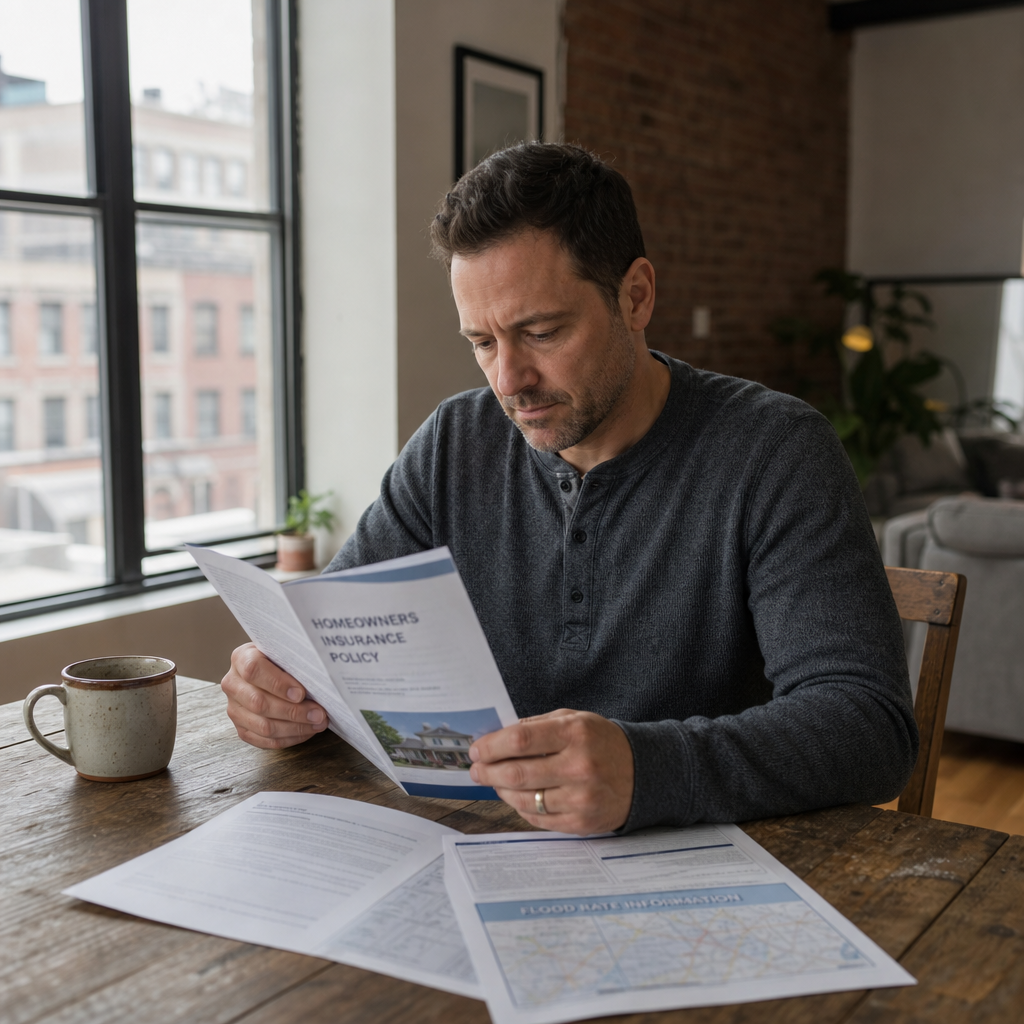
Getting a property restored after water intrusion often comes down to how an insurance policy defines the incident. A common surprise for property owners is learning that standard homeowners insurance policies do not cover flood damage. In the United States, flood protection is primarily sold through the National Flood Insurance Program (NFIP) or private flood insurance options. When rising water or broken pipes damage a building, claims can face delays or denials if the water source is misidentified or insufficiently documented.[1]
Insurance adjusters evaluate claims based on policy definitions and physical evidence. Restoration contractors like Floodline Restoration Co. often utilize moisture meters and documentation to help identify the entry point and spread of moisture. Having thorough documentation can help support the review of your insurance claim.
Does Homeowners Insurance Cover Flood Damage? The Direct Answer
Standard home policies exclude natural, overland flood damage. Events like coastal surges, overflowing rivers, and surface runoff pooling in a yard require a separate policy. For most residential and commercial owners, that policy comes from the NFIP, which serves as the primary provider of flood insurance in the United States with millions of active policies.[3]
Standard Policy Exclusions vs. Covered Sudden Losses
The boundary between what is covered and what is excluded generally depends on the origin of the water. Standard homeowners insurance typically covers sudden and accidental water damage originating from inside the home’s plumbing or heating systems. For example, if an interior supply line bursts, the resulting structural drying and repairs are generally eligible for review under standard homeowners coverage.
Conversely, when water originates outside and flows across the ground before entering a structure, standard carriers classify the event as a flood. This exclusion applies to heavy rain pooling against a foundation, groundwater intrusion, or storm surges from nearby bodies of water. Flood insurance is mandatory for properties with federally backed mortgages located in designated Special Flood Hazard Areas (SFHAs), though flood risk also exists outside mapped high-risk zones.[4]
Key Insurance Takeaways
- Overland Flooding: Excluded by baseline homeowners insurance; coverage requires an NFIP policy or private flood policy.
- Internal Failures: Sudden, accidental internal failures (such as a burst pipe) generally fall under standard homeowners coverage.
- Origin Documentation: Clear documentation helps establish whether water entered from external flooding or originated from interior plumbing.
Water Damage vs. Flood Damage Considerations
Property owners may encounter coverage disputes when water enters a lower level during a severe storm. A primary homeowners carrier may deny a claim if damage is attributed to external rising water, while a flood insurer may evaluate whether the loss meets the policy definition of a general flood condition.
Drain and Sump Considerations: During heavy rain events, municipal storm drains or sump pumps may become overwhelmed. Establishing the specific point of origin through physical evidence is important for determining which coverage may apply.
Sewage Backups and Sump Failure Endorsements
Standard homeowners policies typically exclude municipal drain backups and mechanical sump pump failures. Property owners seeking protection against these events can often purchase an optional water backup endorsement or rider to help cover cleanup and repairs resulting from sump failure or sewer backup, subject to endorsement limits.
| Loss Scenario | Standard Homeowners Policy | Water Backup Rider | NFIP Flood Policy |
|---|---|---|---|
| Burst internal plumbing pipe | Generally Covered (sudden/accidental) | Not Applicable | Excluded |
| Municipal storm sewer backup | Excluded | Covered (subject to rider terms) | Excluded (unless part of a general flood) |
| Surface runoff entering through ground level | Excluded | Excluded | Covered (subject to flood definitions) |
| Rising groundwater seepage through foundation | Excluded | Excluded | Generally Excluded (unless surface flooding inundated the area) |
NFIP Policy Basics
Standard NFIP policies provide defined limits for structural coverage and personal property contents, with separate deductibles applying to each category. Private flood insurance policies may offer different limits and optional coverages depending on the underwriter.[5]
General Restoration Guidance: Structural Considerations
Need homeowners insurance flood coverage?
We’re available now - call for a fast, free estimate.
Note: The following restoration procedures represent general industry practices and considerations rather than policy-mandated rules. Actual restoration requirements vary depending on contractor assessment and site-specific conditions.
Drywall and Insulation Considerations
Porous materials like drywall and batt insulation absorb water rapidly. In situations involving external floodwaters or contaminated water, affected drywall is commonly cut away above the water line, and wet insulation is typically removed to facilitate thorough drying of the wall cavity.
Flooring and Framing Materials
Drying structural materials involves evaluating porosity and water exposure:
| Component | General Restoration Approach | Replacement Considerations |
|---|---|---|
| Hardwood Flooring | Specialized drying equipment may be used for clean water exposure if boards remain stable. | Significant warping, cupping, or exposure to contaminated floodwater. |
| Subfloors | Dehumidification and targeted airflow when materials remain structurally sound. | Delamination, softening, or structural instability. |
| Framing and Studs | Surface cleaning, treatment, and structural dehumidification. | Structural decay or compromised load-bearing capacity. |
General Steps for Filing a Property Water Damage Claim
Taking prompt and organized action can help support the claim evaluation process:
-
Mitigate Further Damage:
If dealing with an active plumbing failure, turn off the main water supply if safe to do so. Address safety hazards, such as electricity in wet areas, and contact qualified professionals like Floodline Restoration Co. to prevent secondary damage. -
Document the Scene:
Take photos and videos of the affected areas, visible water lines, and damaged personal property before major cleanup or disposal begins. -
Maintain Detailed Records:
Keep an itemized inventory of damaged items, contractor repair estimates, and drying records to provide to your insurance adjuster during claim review.
Frequently Asked Questions About Flood Coverage
Does standard homeowners insurance cover natural flood damage?
No. Standard homeowners policies exclude damage from natural overland flooding, overflowing bodies of water, and surface runoff. Coverage for these perils requires a separate flood policy through the NFIP or a private flood insurer.
What is the difference between water damage and flood damage in insurance policies?
In standard insurance terminology, water damage typically refers to sudden, accidental internal discharge from plumbing or appliances. Flood damage refers to external water that flows over the ground before entering the property.
Does homeowners insurance cover water restoration after a pipe burst versus rising groundwater?
A sudden and accidental indoor pipe burst is generally a covered peril under standard homeowners insurance. Rising groundwater seeping through foundations is typically excluded by standard policies and requires specific flood or endorsement provisions.[2]
Is flood insurance mandatory if my home is not in a high-risk flood zone?
Flood insurance is not federally mandated for properties outside FEMA-designated Special Flood Hazard Areas, though property owners in moderate-to-low-risk zones may still choose to purchase coverage.
How is the cost of flood insurance or riders determined?
The cost of a separate flood policy or endorsement depends on various factors, including the property’s location, flood zone designation, structural features, and chosen coverage limits and deductibles.
How do I file a property damage claim for emergency water cleanup?
Contact your insurance carrier or agent promptly following an incident, document the damage thoroughly with photographs and written notes, and retain records from any emergency mitigation contractors, such as Floodline Restoration Co., who assist with the property.
Need homeowners insurance flood coverage?
We’re available now - call for a fast, free estimate.
Sources
- [PDF] national flood insurance program – media toolkit – agents.floodsmart.gov (2025)
- Climate Change, Disaster Risk, and Homeowner's Insurance – cbo.gov (2023)
- Flood Insurance in Communities at Risk of Flooding – cbo.gov (2023)
- [PDF] Flood Insurance in Communities at Risk of Flooding – cbo.gov (2023)
- Homeowners Responses to the New Price of Flood … – afajof.org (2024)
Related reading: Mold Remediation Cost | Call Now-10% Off | Same-Day Service | Free Estimate
Related reading: Emergency Water Removal Near Me | 10% Off & Free Estimate | On-Site in 60 Minutes
Related reading: Emergency Water Extraction – 10% Off & Free Estimate – On-Site in 60 Minutes
Frequently Asked Questions
How do I prove water damage came from an internal pipe burst rather than an excluded flood?
Carriers require physical evidence and moisture mapping to confirm whether water originated internally or entered from the ground level. Floodline Restoration Co. uses advanced moisture meters and forensic photo documentation through our Straight Claim Program to clearly identify entry points and support your claim filing.
Does homeowners insurance require me to wait for an adjuster before starting water extraction?
No, standard property insurance policies contain a mitigation clause requiring homeowners to take prompt action to prevent secondary damage. You can contact Floodline Restoration Co.'s 24/7 emergency dispatch line to begin immediate structural drying while our technicians compile thorough pre-cleanup evidence for your carrier.
What happens if water damage involves both storm runoff and a sump pump failure?
Coverage depends on the specific point of entry and whether your policy includes an optional water backup rider alongside flood coverage. Scheduling a free visual property inspection with Floodline Restoration Co. helps pinpoint the exact source of intrusion, ensuring accurate documentation for both standard and endorsement-specific claims.
About the author
 |
David Harrison David is a certified property restoration specialist with over 12 years of experience in emergency mitigation and structural drying. He holds a degree in Construction Management from the New York Institute of Technology and is an IICRC-certified Master Water Restorer. David specializes in translating complex restoration protocols into actionable advice for property owners navigating unexpected disasters. |
Water damage, flood, or mold emergency?
We’re available now - call for a fast, free estimate.
Call Now - Free Estimate